Four men were injured in a stabbing near Amsterdam Centraal last Saturday, with part of the confrontation broadcast on social media — and commenters egging on the violence.
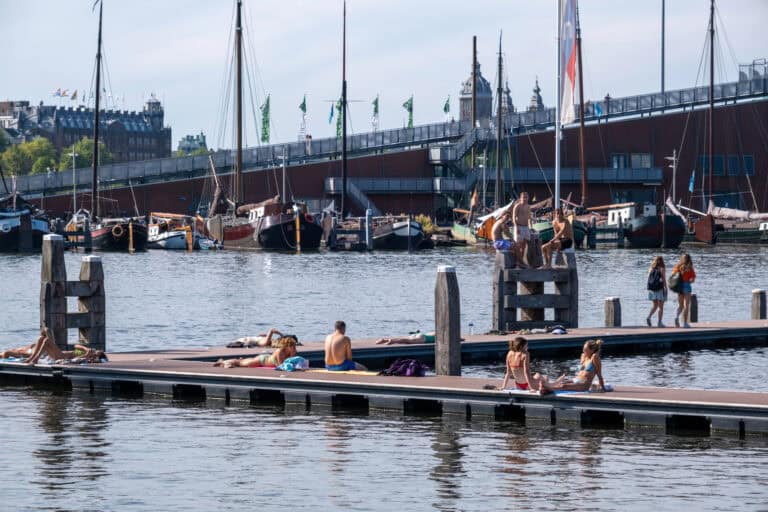
According to a police statement, officers were called to De Ruijterkade on the IJ at around 7:30 PM after multiple reports of a stabbing.
When they arrived on the scene, officers found three victims with stab wounds and an injured suspect. Two of the three victims were transported to hospital, along with the suspect, while the third was treated at the scene.
They have all since been discharged from hospital, and the suspect has now been arrested.
Video evidence is chilling
Various videos of the incident, originally filmed as a TikTok livestream, have spread like wildfire online.
JUST IN: 4 people, including the suspect, stabbed behind Amsterdam Central Station following an argument; incident was reportedly filmed on TikTok Live. pic.twitter.com/BsRPxXUosm
As NOS reports, the footage shows an argument between a TikTok user and a group of men. The person filming repeatedly says “niet aanraken” (don’t touch) before telling the group that he’s “not afraid of six or seven men” and “they’re all going to fall”.
The footage then shows the argument turning physical, with what looks like a knife in the TikToker’s hand.
Meanwhile, responses pour in from fellow TikTok users, encouraging the TikToker to “uithalen” (lash out) and “rammen” (hit violently).
The livestream stops shortly after the TikToker lashes out with a stabbing motion, and someone falls to the ground.
Police are still looking for witnesses
For now, it’s unclear what caused the argument or whether the four men actually knew each other.
The suspect has been identified as a 43-year-old man from Naarden, a town southeast of Amsterdam. However, police have been unable to confirm whether he’s the TikToker who filmed the original video.
Detectives are asking anyone who saw the incident play out (or has more comprehensive footage “from the period before, during, or after the incident”) to come forward.
You can call the police via 0900-8844, anonymously via 0800-7000, through the official tip form, or through the anonymous tip form at Meld Misdaad Anoniem.
The KNMI has issued a code yellow weather warning across the entire country today (August 31), thanks to heavy thunderstorms and wind gusts of 60 to 70 km/h rolling in from the coast.
You’ll want to be careful on your commute this morning, with thunderstorms, strong winds, localised flooding, and even potential hail on the cards.
Here’s what the weather looks like today
The forecast is primarily soggy, with scattered thunderstorms bringing heavy rain over a short period of time. The KNMI predicts that roughly 20-30 mm of rain may fall locally, making for a rather wet commute.
North Holland will get the brunt of our thunderstorms, with even heavier rain. According to the KNMI, “a total of 50-70 mm of rain may fall within 12 to 24 hours”.
Depending on your province, here’s when the rain will hit you:
North Holland: 7 AM to 6 PM
South Holland: 7 AM to 4 PM
Utrecht: 12 PM to 6 PM
Flevoland: 12 PM to 6 PM
Zeeland: 7 AM to 4 PM
North Brabant: 12 PM to 6 PM
Gelderland: 12 PM to 6 PM
Overijssel: 12 PM to 6 PM
Limburg: 12 PM to 6 PM
Friesland: 7 AM to 4 PM
Groningen: 12 PM to 6 PM
Drenthe: 12 PM to 6 PM
By evening, the forecast is expected to become much drier, and there are no active weather warnings for Tuesday.
Potential flooding in North Holland
If you live in the province of North Holland, the KNMI warns of potential wateroverlast (flooding) due to heavy rain.
Commuters also get an extra warning for aquaplaning, which is when a thin layer of water forms between your tyres and the road, briefly causing you to lose control of your vehicle.
Want to make sure DutchReview pops up on your news feed more often? Just add us as a preferred news provider, and we’ll handle the rest.
We all know the Dutch don’t spend money they don’t have to. But there’s more to Dutch financial habits than just splitting the bill at dinner; they’re world-class savers and, increasingly, world-class investors, too.
And that shift matters, because if even the most famously frugal culture in Europe is putting its money to work, it might be worth asking: what do they know that you don’t?
Here’s everything you need to know about saving and investing in the Netherlands — and how you can start making the most of your money while you’re here.
Why are the Dutch so good with money?
The Dutch know-how with money goes back centuries. The Netherlands was home to the world’s first stock exchange: the Amsterdam Stock Exchange, founded in 1602.
With it came a deeply ingrained culture of financial pragmatism. You don’t invent modern capitalism without taking money seriously.
Even when they do “splurge”, Dutch households keep a close eye on their monthly budget. Image: Magnific
Then there’s Calvinisme (Calvinism), the Protestant tradition that shaped Dutch society for generations. Hard work, thrift, and avoiding excess were true virtues. Even as the country has secularised, that instinct to save rather than splurge has stuck around.
The numbers back this up. According to De Nederlandsche Bank (DNB), Dutch households ended 2024 with a record €600.5 billion sitting in savings and payment accounts, having added €24.2 billion over the course of the year.
The Dutch are, in short, exceptionally good at holding onto their money.
But something is changing
Here’s what’s interesting: rather than just holding on to it, the Dutch are starting to invest too.
According to DNB and AFM figures, Dutch household portfolio investments rose by nearly 7.8% in 2025, closing the year at €204.3 billion. Around 2.2 million Dutch households (roughly a quarter of all households) now hold investments.
That said, savings still far outpace investment portfolios. And according to DNB research, Dutch households channel just 23% of their freely available assets into investments — compared to a European average of 36%.
The money-savvy Dutch prioritise having a healthy balance in their savings. Image: Magnific
So the Netherlands remains firmly a savings nation even as investment appetite grows.
Ultimately, this means that if you’re an international in the Netherlands trying to figure out your own finances here, you’re in good company.
Let’s break it down.
First things first: what’s the deal with savings accounts?
Before thinking about investing, it’s worth understanding your banking options.
A deposit savings account is exactly what it sounds like: an account where you put money and earn interest over time. The two main types are:
Easy-access accounts (vrij opneembaar/ spaarrekening — freely withdrawable / savings account), where your money is available whenever you need it. In the EU generally, rates can be as high as 2.85% on freely accessible accounts.
Fixed-term deposits, where you lock money away for a set period in exchange for a higher interest rate — they can go as high as 3.25% p.a., depending on how long you fix for.
So, what about savings accounts in the Netherlands specifically? Unfortunately, Dutch banks have historically offered fairly low interest rates.
A typical interest rate you would see is around 1.25% to 1.45% at major Dutch banks like ABN AMRO. Your money sits there technically earning interest, but not always enough to meaningfully grow your wealth.
Thanks to investment apps, the Dutch have access to higher interest rates outside of the Netherlands. Image: Magnific
This is why many people in the Netherlands are turning to banks in other European countries that offer noticeably better rates.
And accessing them is easier than it sounds. For example, it can be done smoothly using a variety of investment and savings apps.
You can easily compare savings accounts from banks across Europe and open one directly — all from a single account. Need an example? Raisin currently offers a flexible savings account with a yearly interest rate of 2.85%.
Once you have a handle on your savings, it’s time to start thinking about investing in stocks and ETFs. But if you’ve never done it before, it can feel daunting.
Here’s a simple way to think about it: investing means putting your money into assets, like shares in companies or funds, with the hope they’ll grow in value over time.
Unlike a savings account, returns aren’t guaranteed. However, over the long term, investing has historically offered higher growth than keeping money in savings accounts (especially with those low interest rates at your Dutch bank).
So, how do you start your investment journey?
Investment platforms: what they are and why they matter
An investment platform is a service that lets you invest without having to make every individual decision yourself.
Aside from buying individual stocks, many platforms offer portfolio-based investing — where your money is spread across a range of assets, typically ETFs (exchange-traded funds) and index funds.
The Dutch have access to a plethora of investment opportunities via mobile apps. Image: Magnific
ETFs and index funds bundle together many different investments. Instead of betting everything on a single company, your money is spread across dozens or hundreds of them, reducing the risk of any one investment dragging down your entire portfolio.
This is known as diversification, and it’s one of the most widely recommended approaches to long-term investing.
Want to start investing but not sure where to begin? Raisin lets you save and invest from a single account.
Answer a few quick questions about your finances, and you’ll be matched with a portfolio that fits. From there, Raisin takes care of everything: financial experts passively manage a mix of ETFs and index funds, spread across more than 8,000 shares and bonds worldwide. Best of all, you can get started with as little as €25.
Disclaimer: Investing involves risks. You could lose (part of) your investment. Past performance is no guarantee of future results. Raisin Investing is offered by Raisin Bank.
What to consider when thinking of investing
If you’re weighing up whether you should invest, a few things are worth bearing in mind.
Diversification means your money isn’t tied to the fate of a single company or sector. If one investment drops, others may hold steady or rise.
With a diversified portfolio, your risk is spread out over multiple investments. Image: Magnific
Long-term thinking is key. Markets fluctuate in the short term — 2025 saw significant turbulence following US tariff announcements — but diversified portfolios have historically grown over longer periods. The fact that Dutch investors closed 2025 up nearly 8% despite all that market noise says a lot.
Accessibility has improved enormously. You no longer need to be wealthy or financially savvy to start, and many platforms are designed with beginners in mind.
If you’ve got funds sitting in a regular Dutch savings account quietly losing ground to inflation, a fixed-term deposit might be exactly what your money needs.
With lower returns on your cash, locking in a competitive fixed rate through a fixed-term deposit is a move well worth considering.
This guide covers everything you need to know, including:
what a fixed-term deposit is,
the best rates available to residents of the Netherlands right now,
how to open a spaardeposito,
the tax implications,
and answers to any burning questions you may have.
This post might have affiliate links that help us write the articles you love, at no extra cost to you. Read our statement.
What is a fixed-term deposit account?
A fixed-term deposit (known in Dutch as a termijndeposito or spaardeposito) is a savings account where you lock away a lump sum for a set period, in exchange for a guaranteed fixed interest rate (rente).
Depending on your bank, these terms typically range from one month to five years. The most common options you’ll encounter are 3, 6, 12, 24, and 36 months. As a general rule, the longer you’re willing to lock your money away, the higher the rate on offer.
How is a fixed-term deposit different from a regular savings account?
A regular Dutch savings account (spaarrekening) lets you deposit and withdraw freely, but the interest rate is variable. This means that your bank may lower your rate at any time, offering you no real guarantee on how much interest you’ll earn.
Unlike flexible savings accounts, the rate for fixed-term deposits doesn’t change during the term, so you know exactly what you’ll earn from day one. However, there’s a catch: you generally can’t access your money until the term ends without incurring a penalty.
Are you trying to decide if a fixed-term deposit is right for you? These generally suit people who:
have a lump sum they won’t need in the short term,
want certainty over their return,
and want to protect their savings from volatile or falling interest rates.
The best fixed-term deposit rates in the Netherlands right now
We’ve found the highest interest rates, best banks, and best fixed-term deposit accounts to earn interest on your money.
All of the companies below are regulated financial institutions, so your money (up to €100,000 per person, per bank) is guaranteed.
Raisin is a savings platform that offers you access to fixed-term deposits from partner banks across Europe, all through a single account.
Currently, their best fixed-term rates reach 3.60% via Deutsche Bausparkasse Badenia for a 10-year term. Want a shorter term? You can choose from dozens of partner banks across the EU, each offering different rates and term lengths.
📈 Best fixed rate: 3.60% (10 years, via Deutsche Bausparkasse Badenia) 💶 Early withdrawal: Not permitted in most cases 🇬🇧 Available in English: Yes
Most people know Klarna as a buy-now-pay-later service, but the Swedish bank has built a solid savings product for Dutch residents.
Fixed savings rates go up to 3.10% depending on how long you’re willing to lock your money away, with flexible accounts starting from 1.84% per year. Term length is variable; you can select from a range of options that work for your timeline.
📈 Best fixed rate: up to 3.10% (term-dependent) 💶 Early withdrawal: Not permitted 🇬🇧 Available in English: Yes
Trade Republic is an investment platform that pays up to 3% per year on fixed-term savings, with a Fixed Income portfolio that lets you lock in returns through Bond ETFs or individual bonds.
You just pick your duration, lock in your rate, and, unlike a traditional term deposit, you can sell at the current market price if you need to get out early. There are no withdrawal fees, and you can start from just €1.
📈 Best fixed rate: up to 3% 💶 Early withdrawal: Sell anytime; market prices may fluctuate 🇬🇧 Available in English: Yes
Spanish multinational bank Santander currently offers some of the most competitive welcome rates available to Dutch savers, with no monthly costs and a minimum deposit of €1,000.
You can lock in 2.65% for one year with no maximum deposit cap, making it a great way to put a lump sum to work before reassessing at the end of the term.
📈 Best fixed rate: up to 2.65% (term-dependent) 💶 Early withdrawal: Not permitted during fixed term 🇬🇧 Available in English: No (Dutch only)
The Netherlands’ very own neobank bunq makes opening a term deposit as easy as it gets, with no fussy paperwork and an account opened in minutes. Access up to 2.11% with a 12-month plan.
Their term deposits are available for 3 to 24 months, with deposits from €1,000 to €100,000, and your savings are protected by the Dutch Deposit Guarantee Scheme.
📈 Best fixed rate: 2.11% 💶 Early withdrawal: Yes, full withdrawal only; a fee applies 🇬🇧 Available in English: Yes
While ABN AMRO’s rates won’t exactly top the charts, they offer the reassurance of a major Dutch bank alongside fixed deposits you can manage right alongside your everyday account.
Their rates increase with term length: 2% for 1 year, 2.15% for 2, 2.50% for 5 years, and 2.90% for 10 years. Interest is paid annually, and you’ll need an existing ABN AMRO account to open a savings deposit.
📈 Best fixed rate: up to 2.90% (10 years) 💶 Early withdrawal: Possible, but a penalty applies 🇬🇧 Available in English: Yes
Brand New Day is built specifically for pension savings (pensioensparen), combining competitive fixed rates with tax-deductible contributions.
A fixed-term deposit within a Brand New Day pension account currently earns up to 2.90%, above the 2.20% variable rate you’d earn on the standard account. The minimum deposit is €1,000, but you’ll need an existing account to make a deposit.
📈 Best fixed rate: up to 2.90% (10 years) 💶 Early withdrawal: Not permitted; funds reserved for pension 🇬🇧 Available in English: No (Dutch only)
How to open a fixed-term deposit in the Netherlands
The good news is that most fixed-term deposit accounts (including those from foreign EU banks) can be opened fully online.
Here’s what the typical process entails:
Compare rates: Use an online comparison tool or check providers directly. Certain platforms even let you compare multiple EU banks in one place.
Check your eligibility: Most providers require Dutch residency and a Dutch bank account (IBAN) for ID verification and fund transfers.
Verify your identity: This is usually done via an online ID check (passport or ID card) and sometimes a small verification transfer.
Transfer your funds: Once your account is up and running, you can transfer a lump sum to your deposit account.
Wait for your term to complete: Your interest will typically be paid annually or at maturity, depending on the provider you’ve chosen.
Most Dutch banks allow you to transfer funds via the mobile app, making the whole process super convenient. Image: Magnific
What to know about Dutch fixed-term savings accounts
Before you open a fixed-term deposit, there are a few practicalities worth understanding. While none of them is a dealbreaker, they’re all worth knowing before you lock away your cash for months or years.
You can’t withdraw your money freely
Unlike a regular savings account, fixed-term savings lock your money away for the duration of the term.
Most providers don’t allow early withdrawal at all, and those that do may charge you a penalty (generally in the form of denying you some or all of the interest you may have earned).
You’ll want to treat a fixed-term deposit as untouchable until your savings reach maturity. If there’s any chance you’ll need the funds before the term ends, you’re better off opening a flexible savings account.
Your deposit may be auto-renewed
When your term ends, don’t assume that your money automatically lands back in your current account.
Many providers will silently roll your deposit into a new term (likely at a different rate) unless you actively opt out.
Always check your bank’s auto-renewal policy before you open an account, and set a calendar reminder for a week or two before maturity so you’re not caught off guard.
Some providers require minimum deposits
Sadly, not all fixed-term deposits are open to any amount, and minimum deposit requirements can vary quite widely.
Some providers start from as little as €500, while others may require €5,000, €10,000 or more.
Do your research before locking your money away, especially when it comes to minimum rates, auto-renewal policies, and tax requirements. Image: Magnific
Always check the minimum before comparing rates, since the best headline rates sometimes come with the highest entry thresholds.
Your savings will be taxed (even if the rate looks good)
Any interest you earn on fixed-term deposits will fall under Box 3 of the Dutch income tax system.
What this means is that your actual interest income is taxed at a flat rate of 36% on assets above the tax-free threshold (€59,357 per person in 2026). A headline rate of 3% may actually translate to a real after-tax return closer to 1.9% once your Box 3 taxes are factored in.
However, the good news is that if your total Box 3 assets stay below the threshold, you owe nothing. And if you’re an expat on the 30% ruling, you’re exempt from Box 3 tax entirely.
The longer the term, the higher the rate
As a general rule, locking your money away for longer earns you a better interest rate.
A 3-year deposit will typically offer a higher rate than a 1-year one (which in turn beats a 6-month term).
That being said, there are some exceptions. When banks expect further ECB interest rate cuts, some offer relatively competitive, shorter-term rates to attract deposits.
How was your experience opening a fixed-term deposit savings account? Share your thoughts in the comments below.
Fixed-term deposit savings in the Netherlands: Frequently asked questions
What is a fixed-term deposit?
A fixed-term deposit (also known as a termijndeposito or spaardeposito in the Netherlands) is a savings account where you lock away a lump sum for a set period in exchange for a guaranteed fixed interest rate.
Unlike flexible savings accounts, the rate doesn’t change during the term. However, the downside is that you generally can’t access your money until the term ends.
Are fixed-term deposits safe in the Netherlands?
Yes, deposits at Dutch-licensed banks are covered by the Dutch Deposit Guarantee Scheme (Depositogarantiestelsel) up to €100,000 per person, per bank.
Meanwhile, for accounts at foreign EU banks, the relevant EU deposit scheme applies.
What happens when my fixed-term deposit matures?
When your deposit reaches maturity, both your original deposit plus accumulated interest are returned to you.
Some providers will automatically renew your term unless you opt out, so it’s worth checking the auto-renewal policy before you open an account.
Can I withdraw my money early from a fixed-term deposit?
In most cases, you won’t be able to.
While some providers do allow early withdrawal in exceptional circumstances, they will typically apply a significant penalty, usually in the form of reduced or forfeited interest. Certain providers may even charge additional fees on top of that.
Is a fixed-term deposit better than a regular savings account?
It depends entirely on your situation. A fixed-term deposit will almost always offer a higher interest rate than a flexible account, but you won’t have access to your funds for a set period of time.
If you have a lump sum you won’t need for a year or more, and you want a guaranteed, predictable return, a fixed-term deposit is usually the better choice.
Tens of thousands of employees in the Netherlands risk missing out on pension compensation for one truly frustrating reason: they changed jobs at the wrong time during the country’s massive pension overhaul.
The Netherlands is halfway through the process of switching its pension system to a new one, under the Wet toekomst pensioenen (Future Pensions Act).
The new system is intended to be fairer, and move away from the old cycle of younger workers subsiding their older colleagues’ pensions.
However, it comes with one glaring flaw, which could cost many Dutch residents a fair chunk of pension compensation.
Wait, how does that work?
Under the old system (the doorsneesystematiek), younger employees paid relatively more into the collective pot than their older colleagues, effectively subsiding their colleagues’ pensions.
This would come around the longer they stayed with a company; within a few decades, they’d be the ones getting their pensions subsidised. Now, this system is being scrapped.
According to EenVandaag, more than half of Dutch workers are already in a pension fund that has moved to the new system, with the rest due to follow by January 1, 2028.
Who loses out (and why)?
The change primarily affects employees between the ages of 40 and 60, who’ve shelled out pension contributions for years, but will no longer benefit from their younger colleagues’ contributions in the collective pot.
To soften the blow for people who may potentially lose out, pension funds are handing out extra compensation to this group.
However, you can only receive this compensation if you’re an active member of the fund at the moment the pension system switches over.
If you’ve changed employers, gone freelance, or been made redundant, you could likely miss the payout entirely.
In a letter to parliament, Minister of Social Affairs Eelco Vijlbrief estimated that several tens of thousands of people could switch to a new job and pension provider without the necessary compensation this year.
How much money are we talking?
Potentially a LOT. Depending on your age, salary, and pension fund, your compensation could easily run into tens of thousands of euros.
Dutch financial watchdog AFM has floated a rough example of how this might play out:
“Lisa is fifty and has worked at the same company since she was thirty. Her pension fund has informed her that she will transition on January 1, 2026, and expects Lisa to receive compensation of 50% of her pensionable salary. This will result in compensation of €21,763, or an expected €168 per month from the age of 68.”
And these hypotheticals are already playing out in real life, with EenVandaag reporting that hundreds of employees who were laid off at ING are now “missing out on thousands to tens of thousands of euros in pension funds as a result.”
In May alone, AFM stressed the importance of employers and insurers properly informing pension recipients of the changes, including providing them with “realistic expectations of their future pension so that they can take measures themselves if necessary (e.g., making additional contributions).”
What can you actually do about it?
If you’re planning to switch jobs, it’s worth checking which pension fund your current and future employers use, and whether they’ve made the switch to the current system.
Vijlbrief also points out that voluntary continuation of pension build-up, known as vrijwillige voortzetting, is possible for around 93% of active members, based on 2025 fund data filed with regulator DNB.
Because it often applies retroactively from the day you leave, people who only realise later that they’ve missed out can sometimes still qualify for the extra compensation.
Some employers, including ABN AMRO and Philips have built arrangements like this into their plans, while KPN offers a contribution towards it.
Want to make sure DutchReview pops up on your news feed more often? Just add us as a preferred news provider, and we’ll handle the rest.
Despite the many famous Dutch shortcomings in social interaction, one thing they got right is the humble borrel.
Not the borrel itself, mind you, which is often in a crappy bar, with watery beer and half a cup of nuts. That part could be improved upon.
No, the genius lies elsewhere. Really, the borrel represents something greater: a profound, rare, human-to-human (albeit alcohol-stimulated) interaction that predates the internet age.
At the very least, these meet-ups are a reason to get out of the house, which my generation, Gen Z (less-than-lovingly dubbed the “loneliest generation”), desperately needs.
If you’re of an older generation, you may be thinking, “What, these kids need a masterclass on how to have a pint with friends?”
The sad truth is, “Yes, many of us do.”
We may be known for our “Gen Z stares,” TikTok addictions, and for being in a “sex recession,” but what can you expect when we were raised on an unfiltered and unregulated diet of internet exposure, world-shattering political changes, and economic hard truths?
Honestly, I think we should have turned out a lot worse.
Is it really that strange that we want to hide under the covers alone instead of making friends? No. Does that mean it’s a solution? Also no.
If you want a village, be a villager
I believe that the anti-social tendencies of my age group are often not for a lack of trying — we just don’t have the right tools to make community happen.
The reality is that friendship, much like romantic love, is an active process right from the start.
Of course, introductions and meet-cutes can happen accidentally, but maintaining those connections and building on them takes time and effort.
In a world of instant gratification, however, this is a bit of a lost practice.
Not only are perfect social lives perpetually modeled for us on our screens, but the constant dopamine rush from the internet itself is also damaging our ability to be patient and tolerate discomfort.
It’s even been studied: there is a wealth of research dedicated to examining how a lack of impulse control and impatience interacts with high internet use.
With the whole world at our fingertips, why would we need to go out? Image: DepositPhotos.com
Somehow, it’s nice to know my short attention span isn’t totally my fault…
Being social is hard (for some of us)
Alas, creating and remaining in community with other people can be SUPER uncomfortable.
It’s annoying to be social when you don’t feel like it, when it’s inconvenient, when it asks you to sacrifice something. It’s also entirely necessary.
Which no one likes to hear. Especially not people like me (antisocial 22-year-olds).
But unlike our parents, Gen Z has been able to escape this discomfort by retreating online.
We can cosplay interaction with instagram posts and comments, engage in parasocial relationships with influencers who don’t know our first names, and even use AI chatbots as therapists.
Not to mention, we also lived our formative years during a pandemic that suddenly made social distancing and isolation far less taboo.
Remember when social distancing was a thing? Image: DepositPhotos.com
Besides, the rise of influencers and constant guides on how to ‘become a better you’ has made us hyper-focused on personal growth.
Suddenly, it became acceptable to ‘focus on yourself,’ to ‘cut people off,’ and to generally be entirely individualistic in our choices.
It’s even seen as healthy (which makes it even easier to excuse yourself from social norms).
And hey, going to the gym and focusing on yourself rather than going for a drink with friends is, for plenty of reasons, good on paper.
But what happens when that priority of self-improvement and individualism overtakes our ability to be in community with others?
Why the borrel is a cure
Again, the borrel itself doesn’t solve this issue.
But this Dutch practice of regularly meeting up with colleagues, friends, associates, teammates, in a chill place that doesn’t ask you to be productive is…dare I say, restorative?
According to the World Health Organisation, there are nearly 200 million stray dogs worldwide. Impressively, not one of them lives in the Netherlands. It’s the first country in the world without any stray dogs! 👏
Puppies are whisked around the city in bike baskets, most cafés and restaurants are dog-friendly, and small pets can ride on public transport for a reduced price.
This dog-loving atmosphere evidently pays off — but how did the Dutchies do it?
The history of stray dogs in the Netherlands
Owning dogs used to be a sign of status in the Netherlands. Upper-class people owned dogs as pets for sporting purposes, and the poorer masses owned mongrels (mutts) for working purposes.
Many Dutch paintings depict the dogs of ye olden times, such as this one by Joseph Stevens:
Given the intrinsic link to social status, there was a massive dog population in the Netherlands in the 19th century.
Stray dogs in the Netherlands: Dog Carrying Dinner to its Master by Joseph Stevens. Image: Trzęsacz/Wikimedia Commons/Public Domain
However, an outbreak of rabies caused widespread fear of contamination, leading many owners to abandon their (possibly) disease-ridden pets.
As a result, Dutch society’s perspective on the human-dog relationship shifted. The health of a dog came to be seen as a reflection of the owner’s well-being. 🧍🐕
During this time, the Dutch government also introduced a dog tax (hondenbelasting) to try to regulate the number of stray dogs in the Netherlands.
Unfortunately, it had the opposite effect: as many people could no longer afford (or didn’t want to pay) to keep their pet dogs, there were even more strays on the streets.
The Animal Protection Act
The Dutch Society for the Protection of Animals — the country’s first animal protection agency — was founded in The Hague in 1864. A century later, the Animal Protection Act came into effect.
Who wouldn’t love to adopt a little puppy? Image: Pixabay
The act states that it’s forbidden for an owner to abuse any animals, and it’s been updated many times over to continue to ensure animal safety. Under current law, abuse is even punishable by a prison sentence of up to 3 years and a fine of €16,750. 😱
The term “stray dog” can mean many different things:
Free-roaming dogs with an owner: they have an owner, but the owner lets the dog run partially free throughout the day
Free-roaming dogs without an owner: dogs that are abandoned by their owner
Community dogs: dogs that don’t have one owner but are cared for by a community
Feral dogs: dogs that are not cared for by anyone and survive on their own
Stray dogs are usually unwanted because they tend to spread disease and fleas.
Plus, they often cause a mess with human garbage (among other things). Nowadays, there are hardly any stray dogs in the Netherlands, so the country is hailed as victorious for having eradicated the issue. 🙌
How did the Netherlands manage to eradicate its stray dog problem?
Not through euthanasia, thank God.
The Dutch achieved it through the CNVR programme (Collect, Neuter, Vaccinate, and Return), a nationwide, government-funded sterilisation programme. The World Animal Protection Agency believes it’s the most effective way to combat a stray dog population.
Additionally, many municipalities spike taxes for store-bought dogs to incentivise people to adopt homeless dogs from shelters instead. 💖
Further, the Netherlands established an animal police force to monitor crimes against animals. The force also rescues animals in trouble.
Man’s best friend for millennia. Image: Pixabay
“Marianne Thieme, the leader of the Dutch political Party for the Animals (PvdD), thinks there is a correlation between how society treats its animals and how it treats its civilians. She says, “There is a direct link between violence against animals and violence against humans.”
These days, about one in five Dutchies owns a dog after taking a million of them off the streets. 💖
Have you adopted a furry companion yourself? What do you think of this little slice of Dutch history about stray dogs in the Netherlands? Tell us in the comments below!
If you thought it was all in your head that this summer has been especially soup-like and hellish, it’s not. Experts have confirmed that the summer of 2026 is the warmest the Netherlands has ever recorded.
Yep, this summer has been the sweatiest on record, ever since the country started measuring all the way back in 1901.
So, the next time someone tells you you’re being dramatic and you just need to adapt to the summer heat, hit them with these stats.
Let’s talk numbers
Speaking with the NOS, KNMI climate expert Peter Siegmund dishes out the uncomfortable facts:
“We had the highest number of days above 35 degrees, the number of tropical days is higher than ever, never before have we had so many consecutive days with nighttime temperatures of 22 degrees or higher. And it all started in June, normally the least warm summer month.”
NOS also reports that, over the past three months, the average daytime temperature in De Bilt was 19.3 degrees. This beats the previous record of 18.9 degrees set in 2018.
And that half-degree jump? Experts say it’s a big deal.
Indeed, while many of us focus on how hot it is during the day, summer 2026’s nighttime temperatures are getting a special shoutout.
According to NOS, the nighttime temperatures were even more remarkable than those in the daytime, breaking records.
For example, in Maastricht, they had three consecutive nights where the temperature didn’t drop below 22 degrees — that has never happened before.
This will eventually become the norm
Siegmund also carried out some calculations for how often we can expect to see summers like this.
According to him: “If you calculate that ‘return period’ in the current climate, you arrive at five years. That is surprisingly short. So you can expect this once every five years. And that is in the current climate: warming continues, so those five years will become shorter over time.”
Indeed, Siegmund echoes what climate experts around the world have been warning: at this rate, the earth is going to be much hotter in 20 years.
He points out that in recent years, summer temperatures have been higher than the predicted trend line towards KNMI’s highest climate scenario, telling NOS “In the high scenario, this will be an average summer around 2050, in terms of temperature.”
And this could mean a very wet autumn
If you’ve been praying for autumn to come, just know that it will potentially bring plenty of rain showers with it.
While the NOS writes that it is yet to be seen just how this exceptionally warm summer will impact our autumn, the current trend is that Dutch autumns are becoming warmer and wetter.
This isn’t helped by the fact that the sea is currently warmer than usual, which in turn usually leads to heavy rain showers.
The RIVM has confirmed that one person has died in Utrecht as a result of complications caused by the West Nile virus.
Last week, it was announced that a blood donor from the region had tested positive for the virus. This was the first time since 2020 that a person from the Netherlands had contracted the virus here.
However, according to the RIVM, this news does not regard the same person.
A vulnerable person
While the RIVM does not want to reveal too much about the identity of the person out of respect for their family, a spokesperson did confirm to NOS that the person was someone over the age of 80 with underlying illnesses.
About 80% of people who contract West Nile virus experience no symptoms. However, vulnerable groups such as those over the age of 50, and people with compromised immune systems can develop more serious symptoms.
Second death in the Netherlands
The RIVM has also confirmed that a woman from Drenthe, who they suspected of passing from the virus, did indeed have the virus.
In her case, she had contracted the virus while on holiday in southeastern Europe, where her symptoms also started. She passed away last week.
This marks the second death due to West Nile virus that the RIVM has encountered this year.
Can’t be spread from one person to another
The RIVM also points out that it’s basically impossible for humans to spread the virus.
The virus is contracted when a mosquito bites an infected bird. It can then spread the infection to mammals such as horses and humans when it bites them.
However, once a human has symptoms, unless they suddenly have the ability to bite others, they cannot spread it to another person.
The RIVM also points out that the chances of someone contracting the virus in the Netherlands is very low, the chances of someone dying from it, even lower.
Moving to another country can be challenging, and without a significant other by your side, loneliness can creep in.
But before you turn to dating apps, here are six things to know about dating in the Netherlands — specifically, about dating the Dutch! Take it from someone with experience.
Dating in the Netherlands: what’s the deal?
Windmills, tulips, and cheese — the Netherlands is known for many things but what about the people? What do they do, where do they live, what are they like? Most importantly, how do you go about dating one of them?
If you’re hoping to find a tender soulmate to come along and sweep you off your feet, then I have some bad news: the Dutch may not be the right fit.
Welcome to the land of sensibility and realistically romantic folk. 💋
1. Honesty is the way to go
This one goes for both Dutch men and women: honesty is their policy. Don’t worry if you have something stuck between your teeth after dinner, your date will tell you. 🙈
This may come as a shock at first, but once you get used to it, you quickly realise — hey! This is actually better! Who would want to walk around the whole night without anyone mentioning the lipstick on your teeth, right? 🤪
The Dutch believe that it’s better to be honest than to mislead someone or create high expectations. Instead, they put their cards openly on the table so that you don’t have to assume anything.
So, no mind-games, no drama, no fuss! Any doubt? Just ask!
2. Keeping things casual
Dutch people are casual! If you expect to go to a fancy restaurant on a first date, well, things may not turn out the way you want.
Nothing beats the gezellig atmosphere of a traditional Dutch bruin café where you can enjoy a pint and some bitterballen. 😋
Plus, it is just too much work to try to bike with your high heels and itty bitty dress, and who wants to slowly suffocate because of that stupid tie? Lekker rustig, you got this.
That’s why Dutch women and men find it a waste of time to sugar-coat things and shower people with half-fake compliments. So, don’t get discouraged just because your date isn’t complimenting your every trait.
The same goes for romantic gestures. Gifts? Instead of popular ideas like a luxurious box of chocolates, you might get something you would use and enjoy more.
In the end, everyone can get those cliché gifts, but that Kindle they just got for you? That shows not only that your Dutchie cares for you but also listens to what you say and knows what you like! 🤗
4. Marriage, mortgage, and kids in the Netherlands
Okay, this is where things get a little tricky. We’re all familiar with the traditional steps in a relationship.
If you think you’ve found the right person, who you genuinely like spending time with, first you go steady, then after a couple of years, one of you pops the question. Then comes the marriage, a mortgage, and a kid or two — or so the media says. 👀
When it comes to the Netherlands and dating, things go a little differently. They’ve decided to skip all that. Marriage is seen as a serious commitment by many and shouldn’t be taken lightly.
The Dutch aren’t quick to marry. Image: Magnific
So you met someone? Great. Is the relationship going well? Amazing, then let’s move in together and maybe buy a house! Cool. What’s next? How about becoming parents?
I once had a friend of mine say, “First comes the house, then a pet, then a kid, and then the marriage. I’m not going to marry someone without making sure that we can spend the rest of our lives together. What if he is a bad father?” 🤔
5. Taboo who?
It’s not uncommon to hear some heavy-hitting questions like, “Do you believe in God?” and “When was the last time you had sex?” when you’re first talking to a Dutch person.
Surprised? We can only imagine.
Freedom and individuality are encouraged in the Netherlands. Your Dutchie is likely to be someone who isn’t afraid to tackle the trickiest subjects pretty early on in the relationship, if not on the very first date. 😅
The reason? They want to know your opinion on these subjects to evaluate if you two are compatible with each other. That actually makes sense, right?
Moreover, they will give their opinion, whether you want to hear it or not. What the rest of the world considers as potentially rude or too blunt, the Dutch call being open and honest.
6. Like saving money? So do the Dutch!
The Dutch are known for being cheap — ahem, we mean frugal — and this is often seen as something negative, but why?
If your Dutchie knows where the best deals are and doesn’t want to pay extra for something that can be found for less, who says that’s ever a bad thing? 💵 ❤️
Of course, not every Dutch person you date is a cliché
Just like you wouldn’t describe yourself as a typical (insert your home country’s nationality), the same goes for the Dutch as well.
Apart from some common traits that we can mention with humour, it’s better to keep in mind that your Dutchie is just as unique as you!
So, sit back, relax and veelsucces (good luck)in dating a Dutchie!
What’s your experience with dating in the Netherlands? Tell us in the comments below!